প্রকাশের তারিখ : ২৫ অক্টোবর ২০২৬
Ensuring Quality Alongside the Expansion of Islamic Banking Is the Greater Challenge
||
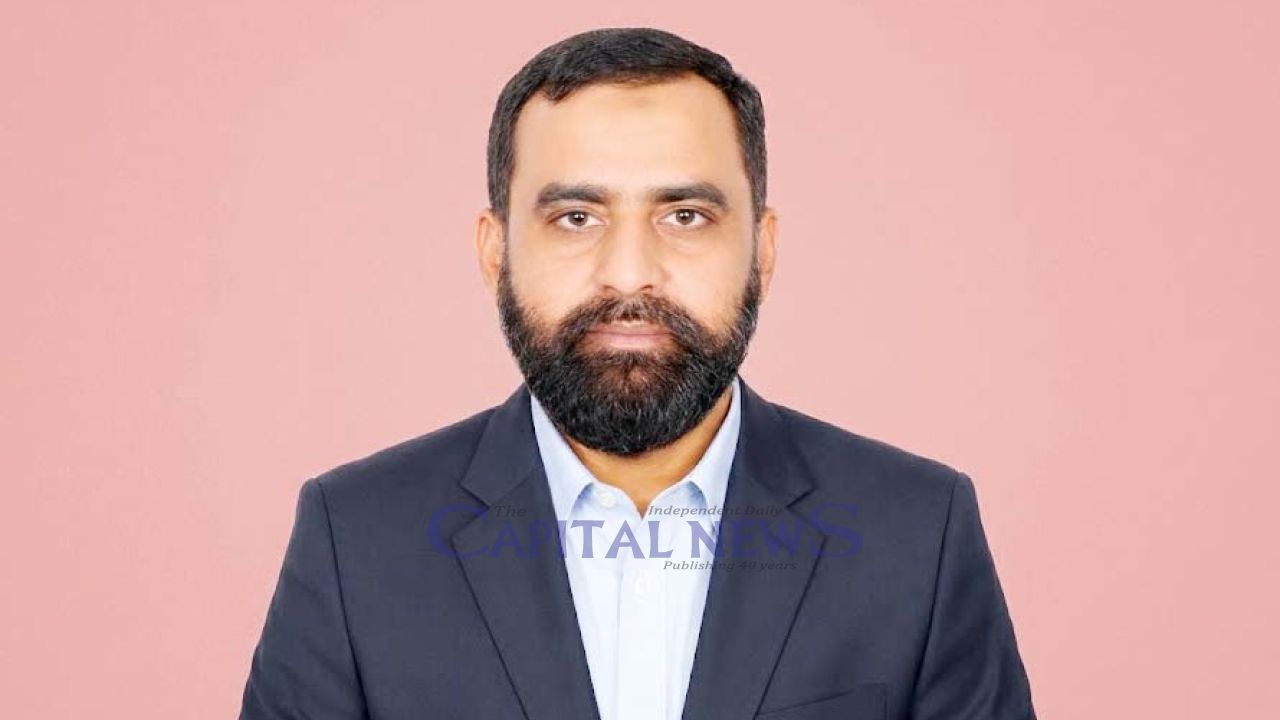
By Md. Mukhlesur Rahman: The objectives of Islamic banking extend far beyond establishing an interest-free framework for financial transactions. They include ensuring equitable financing, promoting the productive use of resources, protecting depositors’ rights, upholding ethical standards in economic activities, and establishing an effective link between financial transactions and the real economy. Achieving these objectives requires a workforce that is honest, competent, well-trained, and accountable. Expanding banking operations under the banner of Islam without developing such capabilities may create new risks instead of delivering the expected benefits.The success of Islamic banking does not depend solely on promotional campaigns, the number of branches and sub-branches, or the use of Shariah-related terminology. Its credibility rests on the integrity, professional competence, Shariah knowledge, training, and accountability of the people responsible for its operations. Banking is a sensitive profession in which incompetence, negligence, conflicts of interest, or unethical decisions can harm depositors, investors, entrepreneurs, and the broader economy. In Islamic banking, these risks are accompanied by the additional responsibility of ensuring Shariah compliance.An Islamic Identity Alone Is Not EnoughThe expansion of Islamic banking is important. However, without a corresponding investment in skilled personnel, strong corporate governance, and effective Shariah oversight, it will be difficult to achieve the desired outcomes simply by establishing new banks or converting conventional banks into Islamic ones. Changing the outward structure is considerably easier than implementing the underlying philosophy, principles, and procedures of Islamic finance in practice.Employees of Islamic banks must understand conventional banking regulations as well as the nature, conditions, risks, and practical applications of contracts such as Murabaha, Ijarah, Mudarabah, Musharakah, Salam, and Istisna. They must also possess expertise in accounting, investment analysis, risk management, financial crime prevention, customer due diligence, and banking law.In Murabaha financing, particular importance must be attached to the proper purchase of goods, acquisition of ownership, possession, assumption of risk, and subsequent sale. In partnership-based financing arrangements such as Mudarabah and Musharakah, a clear understanding of profit distribution, loss allocation, accounting transparency, and the rights of the parties is essential. A transaction does not automatically become Shariah-compliant merely because it carries an Islamic name. The relevant conditions must also be fulfilled in actual practice.Integrity and Competence Must Go Hand in HandIntegrity is as essential as competence in banking. An employee may be highly skilled, but if that person is unethical, those skills can be misused, resulting in substantial financial losses. Conversely, even an honest and well-intentioned employee may make mistakes in complex investment decisions, risk assessments, or the implementation of Shariah contracts without adequate training. Integrity and competence must therefore be treated as complementary requirements, not alternatives. Both must be supported by a strong sense of professional responsibility, safeguards against conflicts of interest, and effective accountability mechanisms.The Holy Qur’an instructs believers to return trusts to their rightful owners and to uphold justice when making judgments among people (Surah An-Nisa, 4:58). In light of these principles, institutions that depend on public trust, particularly banks, should prioritize integrity, qualifications, and competence in recruitment, promotion, and the allocation of responsibilities.Assigning important positions solely on the basis of religious or political identity, formal certificates, or recommendations from influential individuals may not produce the desired results. Recruitment must involve a careful assessment of relevant knowledge, practical skills, professional experience, and ethical standards. Continuous training and regular performance evaluations must also be ensured after appointment.Integrating Shariah Knowledge with Modern Banking ExpertiseBoth Shariah scholars and banking professionals have important roles to play in Islamic banking. Shariah scholars examine the jurisprudential validity of contracts, while banking professionals assess their practical implementation, financial risks, accounting requirements, and compliance with regulatory provisions. Without effective coordination between these groups, a gap may emerge between policy decisions and actual banking operations.Effective coordination is therefore necessary among Shariah boards, management, internal Shariah audit units, risk management departments, and conventional audit functions. The independence of Shariah boards must be safeguarded so that commercial interests or management pressure cannot unduly influence Shariah-related decisions. Adequate staffing, access to information, and audit facilities must also be provided to verify whether board decisions are being implemented properly.The mere approval of a transaction or policy by a Shariah board does not establish that every related transaction has been Shariah-compliant in practice. Regular monitoring is necessary to determine whether approved policies and procedures are being followed. When deficiencies are identified, their causes must be investigated promptly, responsibility must be established, and corrective measures must be taken.The Risks of Islamic Banking in Name OnlyIf the expansion of Islamic banking becomes merely a strategy for commercial competition, market growth, or attracting customers by exploiting religious sentiment, its fundamental purpose is seriously undermined and may even become deceptive. If banks change only the names of their products while conducting business without maintaining the essential contractual distinctions between conventional interest-based lending and Islamic financing, the credibility of their Shariah compliance may be called into question.Weak investment appraisal, irregular financing, conflicts of interest, political or personal influence, and a lack of accountability can expose Islamic banks to serious problems. An Islamic identity does not automatically protect an institution from these risks. Indeed, depositors and customers may place additional trust in such institutions because of their religious identity, making the consequences of misconduct even more serious. Irregularities at one bank can undermine public confidence in the entire sector. Shariah compliance must therefore be embedded in institutional culture and internal control systems rather than treated as a matter of publicity.What Must Be Done to Develop Human ResourcesFirst, a standardized and continuous training framework must be established for Islamic banking. Depending on their responsibilities, bank officers, branch managers, investment officers, auditors, and senior executives should receive training in Shariah principles, accounting, risk management, financial analysis, banking law, consumer protection, and professional ethics.Second, training must not be reduced to the formality of obtaining certificates. Employees’ capabilities should be assessed through practical exercises involving case studies, contract verification, investment appraisal, and the identification of irregularities. Competency examinations and refresher training should also be introduced where necessary.Third, cooperation among universities, training institutions, banks, and Shariah scholars should be strengthened. Research-based education in Islamic economics, Islamic finance, banking technology, and risk management should be expanded. Research findings must also be translated into practical policies and institutional reforms.Fourth, transparency in recruitment and promotion must be ensured. Integrity, competence, experience, and performance should take precedence over political affiliation, personal relationships, or unquestioning loyalty to influential individuals. Independent mechanisms for investigating irregularities, protection for whistleblowers, and accountability proportionate to individual responsibilities must be established.Fifth, banks should publish reliable reports on their Shariah compliance and financial governance. Relevant information concerning audit findings, corrective measures, and material risks should be made available to depositors and regulatory authorities. Meaningful transparency is possible without compromising legal requirements or customer confidentiality.Strengthening the Foundation Before Expanding FurtherThe future of Islamic banking depends on more than opening new branches or increasing the number of customers. The safety of depositors’ money, the productivity of investments, the transparency of contracts, the effectiveness of Shariah compliance, and the accountability of institutions are all important measures of success.The objective should not be to discourage the expansion of Islamic banking, but to improve the quality of its workforce, institutional capabilities, and regulatory safeguards in line with that expansion. Sustainable Islamic banking cannot be built on a workforce that is honest but incompetent, or competent but dishonest. What is needed is a combination of integrity, professional expertise, Shariah knowledge, continuous training, and effective accountability.Bridging the gap between the outward identity of Islamic banking and its actual operations is a shared responsibility of banks, regulatory authorities, Shariah scholars, and training institutions. The credibility of Islamic banking is not merely a commercial asset; it is also closely connected with religious trust, the security of deposits, and the stability of the financial system.Therefore, the fundamental prerequisite for the sustainable development of Islamic banking is the creation of an honest, competent, well-trained, and accountable workforce. Expanding banking operations under the banner of Islam without strengthening this foundation may jeopardize Shariah compliance, depositors’ confidence, and overall financial stability rather than deliver the benefits that Islamic banking is intended to provide.By Md. Mukhlesur RahmanIslamic Finance Specialist, Economist, Social and Political Thinker, Geopolitical Analyst, and Human Rights Activist
© 2025 The Daily Capital News