প্রকাশের তারিখ : ১৫ নভেম্বর ২০২৬
Why should taxpayers bear the cost of the banking sector's collapse?
||
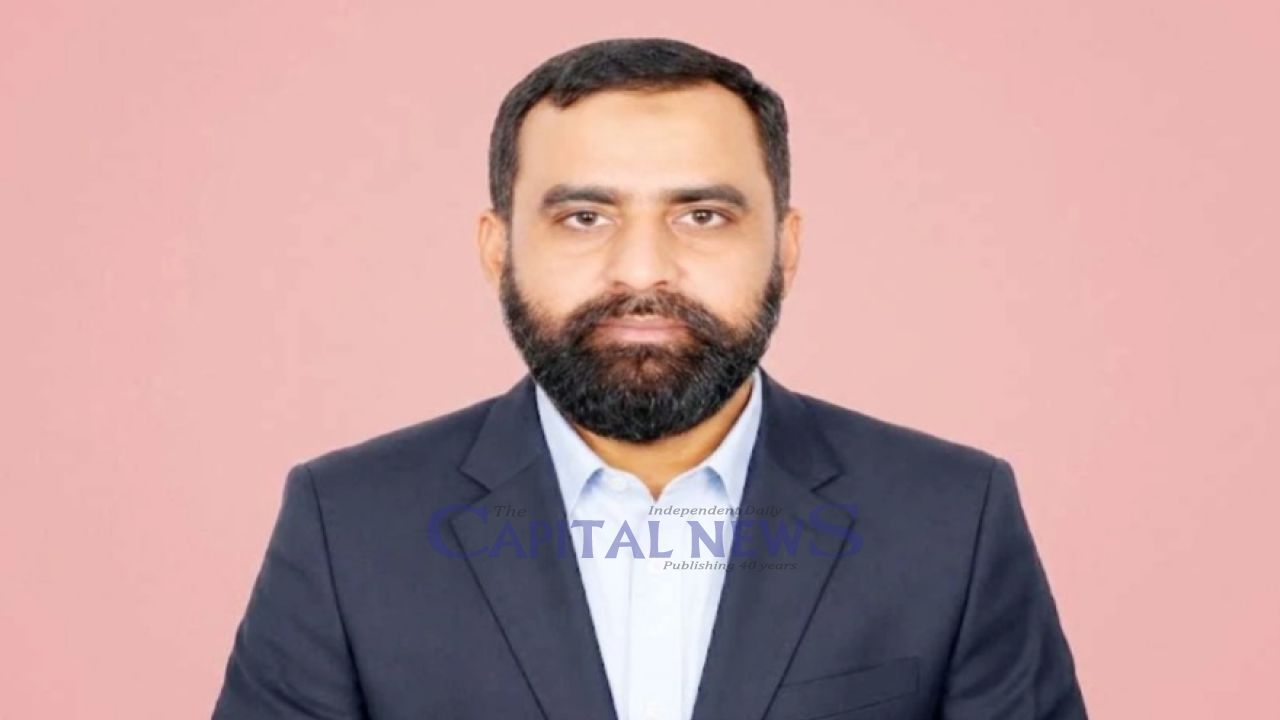
Md Mukhlesur Rahman: The Governor of Bangladesh Bank has recently stated at various public events that the banking sector may require an annual allocation of Tk 60,000 crore from the national budget for its recovery. He has also indicated that such allocations may be necessary for the next eight years. This means that the total expenditure from the public exchequer could reach approximately Tk 480,000 crore over that period.Ultimately, the burden of this enormous financial loss in the banking sector will fall on ordinary taxpayers. Why should ordinary citizens bear the financial consequences of those individuals and institutions against whom allegations of irregularities in obtaining bank loans, misuse of borrowed funds, or money laundering have been raised? There is no principle in Islam, nor any provision in the prevailing legal framework, that allows one person to be held responsible for another person’s wrongdoing.The current crisis in Bangladesh’s banking sector did not emerge overnight. It is the consequence of years of weak supervision, political interference, irregularities in loan approvals, governance failures, and the lack of effective action by regulatory authorities. Various business groups, including S Alam Group, Beximco, Nassa, AnonTex, Crescent and Thermax, have faced allegations at different times concerning irregularities in obtaining and utilising bank loans, concealing the actual destination of borrowed funds, and transferring money abroad. It is difficult to believe that such extensive banking irregularities could have taken place without the direct or indirect patronage of the then government. Nevertheless, these allegations must be addressed through impartial investigations, evidence gathering, and due legal process to establish accountability.Not every defaulted loan constitutes embezzlement or a criminal offence. However, if evidence establishes that loans were obtained through fraud, forged documents, misrepresentation of collateral values, diversion of funds from their approved purposes, or deliberate attempts to evade repayment, such conduct may constitute offences under the relevant laws. Therefore, it is essential to distinguish between ordinary loan defaults and organised financial misconduct when determining the actual causes of losses in the banking sector.What Do the Non-Performing Loan Figures Reveal?According to data published by Bangladesh Bank, the volume of non-performing loans (NPLs) in the country’s banking sector stood at Tk 606,555 crore at the end of June 2026, representing approximately 32.78 per cent of total loans. However, the situation varies considerably from one bank to another. While some banks have managed to keep their NPL ratios relatively under control, several others have reached alarming levels.This disparity raises important questions. It is true that political changes have created uncertainty in business and commerce, while economic pressures have intensified. However, the wide differences in NPL ratios among banks operating under broadly the same economic conditions cannot be explained away simply by referring to the deterioration of the business environment.Of course, not all non-performing loans result from financial crimes. Genuine business losses, market downturns, and other economic factors can also disrupt loan repayments. Nevertheless, when almost the entire loan portfolio of a bank becomes non-performing, a thorough investigation into loan approvals, collateral verification, utilisation of loan proceeds, and the effectiveness of management becomes imperative.The Roles of Bank Officials Must Also Be InvestigatedIn cases involving enormous amounts of unpaid loans, investigating only the borrowers’ liabilities will not be sufficient. The decisions and roles of the relevant bank boards of directors, managing directors, loan-approving officials, internal audit departments, and risk management personnel must also be examined.Investigators should determine whether proper due diligence was conducted before approving the loans, whether the borrowed funds were used for their designated purposes, and whether appropriate action was taken after irregularities came to light.Similarly, the performance and responsibilities of the relevant supervisory officials of Bangladesh Bank must be reviewed. If loan irregularities and financial weaknesses persist in a bank for years, it is essential to investigate whether there were shortcomings in regulatory oversight. If evidence establishes that officials knowingly ignored irregularities, concealed information, or neglected their duties, appropriate action must be taken against them under the applicable laws and regulations.Allegations of unethical interference by political figures or government officials in the formation of bank boards, changes in ownership, or loan disbursement must also be subjected to independent and impartial investigation. No individual or institution should be declared guilty merely on the basis of allegations. However, where irregularities are established through evidence, the law must be enforced without favour or discrimination, regardless of the identity or influence of those involved.Accountability Must Come Before the Use of Public MoneyState assistance may be necessary to restructure the banking sector. When a bank becomes distressed, ordinary depositors, small entrepreneurs, and the wider economy suffer. Therefore, the government has a responsibility to safeguard financial stability. However, providing state assistance does not mean that the financial consequences of past irregularities and mismanagement should be transferred to the public without scrutiny.Government revenue comes from taxpayers. These resources are expected to support education, healthcare, agriculture, social protection, and infrastructure development. Against this backdrop, the proposal to allocate Tk 60,000 crore annually from the national budget to address the banking crisis raises serious fiscal and policy concerns. Before public funds are committed, the actual causes of the losses must be established, those responsible must be identified, and lawful efforts must be undertaken to recover the money.Investigations into borrowers facing allegations of fraud, misuse of funds, or money laundering must be completed as quickly as possible. The sources and ownership of assets held by such borrowers and their associated institutions, both at home and abroad, should be examined. Where illegally acquired assets are identified, steps should be taken to freeze, seize, and confiscate them through appropriate legal procedures. International cooperation should also be pursued, where necessary, to recover funds transferred abroad.The public expects the Governor of Bangladesh Bank not merely to highlight the need for budgetary allocations, but also to disclose transparent information about the actual extent of losses in the banking sector, the nature of irregularities, the progress of investigations, and initiatives undertaken to recover misappropriated funds.If public money is provided to any bank, there must be clear mechanisms to ensure transparency in its utilisation, accountability in management, and a credible plan for recovering the financial assistance.Restoring public confidence in the banking sector requires more than financial restructuring. It demands the rule of law, good governance, and institutional accountability. Those against whom allegations of loan fraud, misappropriation of funds, or money laundering are established through proper investigation must be held accountable, and the money must be recovered from them in accordance with the law. The financial burden of such crimes must not be imposed on ordinary taxpayers.The recovery of the banking sector is essential in the public interest. However, in the process of restoring the sector, citizens must not be forced to bear the financial consequences of irregularities and corruption committed by others.Md. Mukhlesur RahmanEconomist, Islamic Finance Specialist, Social and Political Thinker, and Human Rights Activist.
© 2025 The Daily Capital News