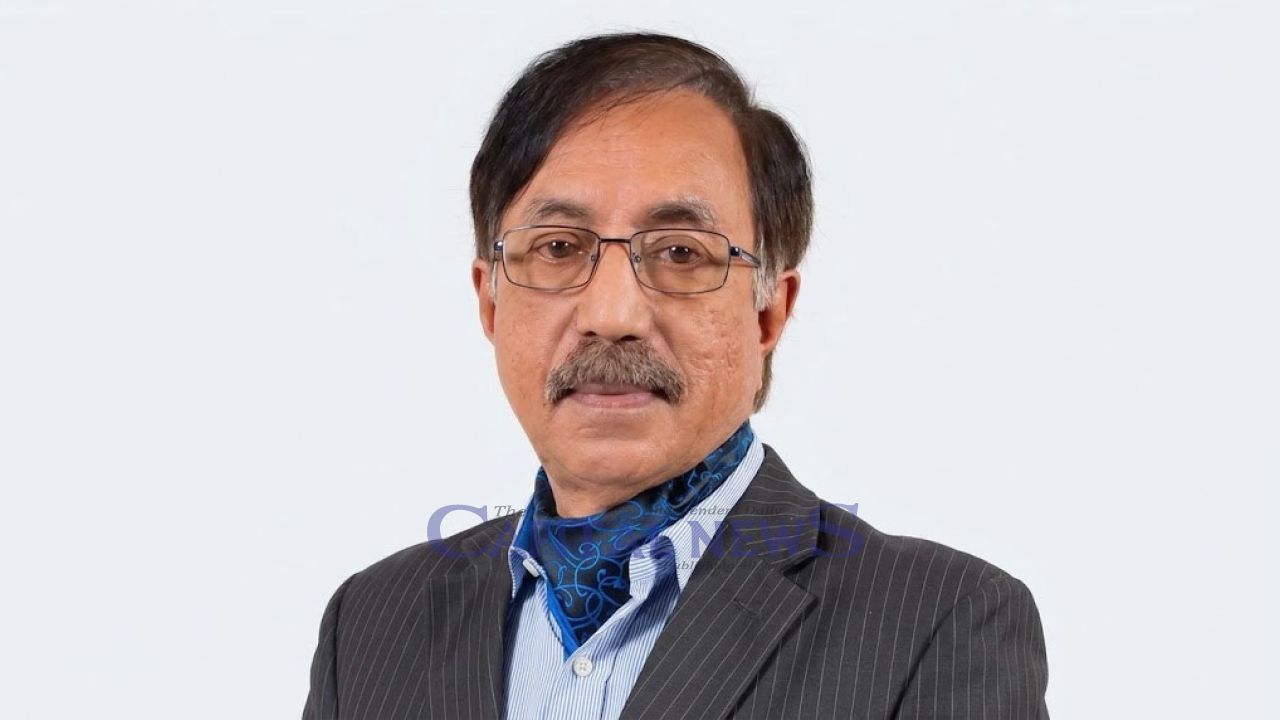
By Imtiaz Ahmed: Faruq Mayeenuddin Ahmed, Independent Director & Vice Chairman and Chairman, Executive Committee of the Board, BRAC Bank PLC, in an interview with Imtiaz Ahmed of the Bangladesh Mail, said that Bangladesh can stabilize its banking sector by ensuring absolute independence of the central bank, drastically reducing non-performing loans and eliminating politically motivated boardroom loan sanctioning.
A brilliant economics graduate of Dhaka University, he has served in senior management roles at Trust Bank (MD and CEO), City Bank (AMD, Chief Risk Officer and Chief Anti-Money Laundering Compliance Officer, CAMLCO), AB Bank (DMD) and Mercantile Bank (DMD), and is now also an Adjunct Faculty member at East West University.
Bangladesh can stabilize its banking sector by ensuring absolute independence of the central bank, drastically reducing non-performing loans and eliminating politically motivated boardroom loan sanctioning.
The rest of the interview is given below:
1. The Bangladesh economy has been battered by the COVID-19 pandemic, the Russia-Ukraine war, war and tensions in the Middle East, plundering of bank money and a slowdown in global growth. How do you see the prospects of the Bangladesh economy in the 2026–27 fiscal year?
Albeit the Bangladesh government projected an ambitious target of 6.5% GDP growth, all the international agencies like ADB, HSBC and IMF have forecast much lower growth of 4%, 4.4% and 3.5%, respectively. We need to consider that the economy has been under severe stress in the banking sector, with high non-performing loans and weak balance sheets of most of the banks. We are experiencing the lowest private-sector credit growth, which will hold back investment further. The unstable energy sector will act as the highest barrier to investment. The latest hike in fuel prices is the strongest blow to new investment, in addition to fueling inflation further.
All these factors will spoil any prospect for the economy, with no sign of recovery in the near future.
2. How do you see the success of the Bangladesh economy during the last 54 years?
Bangladesh had been a poverty-stricken, agrarian country in the year of its liberation. In the last 54 years, it has been transformed into a vibrant lower-middle-income industrial economy. Major successes have been achieved in many sectors that have posed the country as a paradox to the international community.
Our extreme poverty was nearly 80% in the early 1970s and roughly 50% in 1991, which dropped to about 18.7% by 2024, aided by expanding social safety nets.
The Ready-Made Garments sector expanded dramatically, generating over 80% of total export earnings and employing millions of local workers, particularly women. As a result, a large number of women found the light of empowerment, which has largely been substantiated by the income-generating activities of NGOs aimed at reducing gender disparity.
Bangladeshi farmers and researchers achieved self-sufficiency in staple food grain production, pushing output to roughly 35 million tons annually. We have already secured a position among the world's leading producers of fish and vegetables, while achieving notable self-sufficiency in the meat, poultry and cattle sectors. We have become the 2nd largest producer of freshwater fish in the world.
We rank 3rd in overall vegetable production, producing millions of tonnes annually and securing top-10 positions for specific crops like potatoes and tropical produce.
Bangladesh has achieved self-sufficiency in meat production, generating output that outpaces domestic demand. Our commercial poultry and egg sector has expanded sharply by over 200% in the past decades, making the country self-sufficient in egg and poultry meat supply while providing extensive rural employment.
Remittances sent by Bangladeshi wage earners have become a strong pillar for foreign exchange reserves and macroeconomic stability. Bangladesh started its journey with just around US$24 million in the early 1970s, which increased to a record US$32.8 billion in 2025.
3. According to the latest data of Bangladesh Bank, total NPLs in the banking sector stood at Tk6,06,555 crore at the end of June, equivalent to 32.78% of total defaulted loans. In other words, nearly Tk33 out of every Tk100 lent by banks was classified as non-performing. How can the Central Bank be constructive in improving the health of the banking sector?
The central bank can improve the health of the banking sector by enforcing rigorous oversight, risk-based supervision, eliminating interference of the Board in lending, and tightening the credit assessment matrices of banks with high NPLs. Other required measures are:
• Shift from rigid rule-based oversight to dynamic, real-time risk tracking across commercial bank clusters.
• Weak and high-NPL-ridden, non-viable banks must be restructured through mergers and other strategic changes.
• Aggressively reduce non-performing loans through transparent write-off guidelines and recovery drives.
• Anonymous and fraudulent lending should be separated from NPLs and booked under the Protested Bill head of the balance sheet, which is done in cases of fraud in the bank.
4. The distribution of loans in the rural sector is a major challenge in Bangladesh. How do commercial banks work with the central bank in reaching loans to the rural economy?
The central bank, through its policy directives, refinancing facilities and target quotas, can induce commercial banks to expand affordable credit into the rural economy. The central bank sets mandatory quotas for commercial banks to allocate a specific percentage of total loans to agriculture and rural sectors. Regulators have also made it mandatory for commercial banks to maintain a ratio of rural branches compared to urban branches. The central bank can provide low-cost refinancing funds to commercial banks specifically for disbursing agricultural or CMSME loans. In the latest move by the government, the central bank has introduced a number of incentive and refinance packages for CMSME loans in rural and semi-urban areas.
5. The central bank had poorly supervised the banking sector as political intervention was too high during the tenure of the last political government. How do you see the supervision of the central bank nowadays?
In January 2026, Bangladesh Bank officially rolled out the Risk-Based Supervision (RBS) framework. Under the changed arrangements, the central bank reorganized its internal structure by dissolving 13 traditional onsite/offsite supervision departments into 17 specialized units. BB now continuously monitors the custom risk profiles, liquidity exposures and data accuracy of banks in real time, shifting from compliance checks to early intervention.
After the political shift of 2024, the central bank initiated aggressive actions, utilizing the Bank Resolution Ordinance 2025 to acquire or forcefully restructure distressed bank boards, freeze troubled assets, and attempt recovery of laundered funds. Financial authorities implemented stricter loan classification guidelines, which brought hidden default loans to light.
6. Foreign direct investment (FDI) flow to Bangladesh suffered over the last two years against the backdrop of political instability, poor governance and a poor law-and-order situation. The present government is working hard to improve the business environment. How do you evaluate the investment climate in Bangladesh?
It's true that Bangladesh lags behind competing countries in attracting foreign direct investment (FDI). World Bank data shows that in 2024, Bangladesh received USD 1.53 billion in FDI, while India attracted USD 27 billion, Indonesia USD 21 billion, and Vietnam USD 20 billion. Vietnam's FDI has demonstrated an increasing trend for three consecutive years.
The interim government bragged a lot about bringing a young banker from abroad to appoint to the top position at the Bangladesh Investment Development Authority (BIDA). But the investment climate has not improved to a satisfactory level. Instead, new foreign investment has declined. An example can be cited that the interim government cancelled renewable energy deals with 31 companies signed during the Awami League government. Even Transparency International Bangladesh had expressed deep concern over this decision to cancel the renewable energy projects involving an estimated investment of around $6 billion. It warned that the move could undermine investor confidence at a critical time for Bangladesh's clean energy transition.
Although the present government has been trying to bring back the confidence of investors, the success appears to be a far cry amid the present law-and-order and energy situation of the country. In a situation where even local investors are shying away from investing, we cannot expect foreigners to come forward to invest here.
8. The unethical political intervention in the banking sector during the tenure of the last political government was a black part in the history of the banking sector of the country. How can Bangladesh overcome the major challenges in stabilizing the banking sector?
Bangladesh can stabilize its banking sector by ensuring absolute independence of the central bank, drastically reducing non-performing loans and eliminating politically motivated boardroom loan sanctioning. The central bank should be given regulatory and operational independence, free from all political interference. Transition gradually to strict asset classification, transparency and risk-based supervision, shunning the rescheduling culture of overdue loans based on political decisions. Legal support should be ensured for banks to fight against willful defaulters so that they can be brought under strict legal recourse.
9. Local and export-oriented industries have become victims of the energy crisis nowadays. The USA-Israel-imposed war on Iran has created instability in the global energy markets. According to newspaper reports, a number of industrialists have either partially cut production. How do you see this scenario as a banker?
From a banking perspective, the energy crisis hitting all types of industries will have a chain reaction on credit risk, liquidity and economic stability. When factories cut production due to power outages or high fuel costs, their financial distress immediately transfers to the balance sheets of commercial banks. There will be a surge in non-performing loans, a reduction in cash flow due to lower output and missed export deadlines. With revenues plummeting, industries will have to struggle to generate the cash flow required to service their debts, which eventually will lead to a rising tide of classified loans. When production in export-oriented industries drops, foreign exchange inflows will dry up, worsening national dollar/foreign currency liquidity shortages. Due to the FX shortage, banks will struggle to open Letters of Credit for raw materials and machinery. This will create a vicious cycle: industries cannot import raw materials to produce goods, further damaging their ability to repay banks.
10. Every year, commercial banks have plans to launch new projects. Can you brief us about your new projects?
In fact, it is more important to ensure sustainable growth than merely launching new projects. We see all the improvement initiatives as projects that are visible in the bank's coveted performance. We have introduced the "Missing Majority" strategic vision during its 25th-anniversary silver jubilee celebration to expand financial inclusion to the 72% unbanked population of Bangladesh. If you ask for a project, then our present project is moving beyond the long-standing "Missing Middle" focus on SMEs to a retail banking mission targeting the broader unbanked population and leveraging digital tools, data and agent banking to deliver personalized services regardless of geography or income level.
Short Biodata
Faruq Mayeenuddin Ahmed
BSS (Hons), Economics, MSS, Dhaka University
Independent Director & Vice Chairman and
Chairman, Executive Committee of the Board, BRAC Bank PLC
Adjunct Faculty, East West University
Former AK Gangopadhya Chair Professor,
Bangladesh Institute of Bank Management
Former MD and CEO, Trust Bank
Former Additional MD, The City Bank
Former Deputy Managing Director, AB Bank and Mercantile Bank Ltd
Mr. Ahmed is a leading name in the banking and financial sector of Bangladesh, where his career spans over four decades. A brilliant economics graduate of Dhaka University, he has served in senior management roles at Trust Bank (MD and CEO), City Bank (AMD, Chief Risk Officer and Chief Anti-Money Laundering Compliance Officer, CAMLCO), AB Bank (DMD) and Mercantile Bank (DMD). He also led AB Bank's India operations from 1999 to 2004. Presently, he is the Independent Director and Vice Chairman of BRAC Bank Ltd and Chairman of the Executive Committee of the Board, responsible for reviewing and sanctioning credit proposals. Presently, he is an Adjunct Faculty member of East West University's Business Faculty.
In the banking sector, Mr. Ahmed specializes in risk management and mitigation, compliance, credit operations and administration, branch operations, anti-money laundering, international trade and strategic management. He was actively associated with the formation of the Association of Anti-Money Laundering Compliance Officers of Banks in Bangladesh (AACOBB) and was the Founder Chairman.
Aside from his industry roles, Mr. Ahmed taught at Dhaka University as Guest Faculty in the Department of International Business (2017–2018) and the Department of Organization Strategy & Leadership (2021), and at the Bangladesh Institute of Bank Management on Corporate Governance (2021). In addition, he is occasionally invited as a guest resource person at different universities and other financial institutions. He is well known and highly respected as a leader and mentor both in the industry and academia.
Mr. Ahmed is a published author and received the prestigious Bangla Academy Award in 2020 for his contribution to Bangla literature. He has so far authored nearly three dozen books on banking, finance, the share market, translation, short stories, travelogue and literary articles. He is also a regular contributor to national dailies and a discussant in electronic media on banking and economic issues.
Education
MSS in Economics, Dhaka University, 1980
MSS in Economics, Dhaka University, 1981
Awards and Recognitions
• IFIC Bank Literary Award 2011 for excellence in translation of the book A Poet Apart by American scholar Clinton B. Seely.
• City-Ananda Alo Award for travelogue 2019.
• Bangla Academy Literary Award 2019.
• Bangladesh Bank and BCCI (erstwhile) Gold Medal for securing the first position in the Banking Diploma Examination 1987.
Subject : Faruq Mayeenuddin Ahmed
সোমবার, ১৯ অক্টোবর ২০২৬
Publish Date : 23 September 2026
Write Your Opinion